Showing posts with label Wall Street. Show all posts

Monday, July 29, 2019

A Bank With 49 Trillion Dollars In Exposure To Derivatives Is Melting Down Right In Front Of Our Eyes


TECB
Could it be possible that we are on the verge of the next “Lehman Brothers moment”?  Deutsche Bank is the most important bank in all of Europe, it has 49 trillion dollars in exposure to derivatives, and most of the largest “too big to fail banks” in the United States have very deep financial connections to the bank.  In other words, the global financial system simply cannot afford for Deutsche Bank to fail, and right now it is literally melting down right in front of our eyes.  For years I have been warning that this day would come, and even though it has been hit by scandal after scandal, somehow Deutsche Bank was able to survive until now.  But after what we have witnessed in recent days, many now believe that the end is near for Deutsche Bank.  On July 7th, they really shook up investors all over the globe when they laid off 18,000 employees and announced that they would be completely exiting their global equities trading business…
It takes a lot to rattle Wall Street.
But Deutsche Bank managed to. The beleaguered German giant announced on July 7 that it is laying off 18,000 employees—roughly one-fifth of its global workforce—and pursuing a vast restructuring plan that most notably includes shutting down its global equities trading business.
Though Deutsche’s Bloody Sunday seemed to come out of the blue, it’s actually the culmination of a years-long—some would say decades-long—descent into unprofitability and scandal for the bank, which in the early 1990s set out to make itself into a universal banking powerhouse to rival the behemoths of Wall Street.
These moves may delay Deutsche Bank’s inexorable march into oblivion, but not by much.
And as Deutsche Bank collapses, it could take a whole lot of others down with it at the same time.  According to Wall Street On Parade, the bank had 49 trillion dollars in exposure to derivatives as of the end of last year…
During 2018, the serially troubled Deutsche Bank – which still has a vast derivatives footprint in the U.S. as counterparty to some of the largest banks on Wall Street – trimmed its exposure to derivatives from a notional €48.266 trillion to a notional €43.459 trillion (49 trillion U.S. dollars) according to its 2018 annual report. A derivatives book of $49 trillion notional puts Deutsche Bank in the same league as the bank holding companies of U.S. juggernauts JPMorgan Chase, Citigroup and Goldman Sachs, which logged in at $48 trillion, $47 trillion and $42 trillion, respectively, at the end of December 2018 according to the Office of the Comptroller of the Currency (OCC). (See Table 2 in the Appendix at this link.)
Yes, the actual credit risk to Deutsche Bank is much, much lower than the notional value of its derivatives contracts, but we are still talking about an obscene amount of exposure.
And this is especially true when we consider the state of Deutsche Bank’s balance sheet.  According to Nasdaq.com, as of the end of last year the bank had total assets of 1.541 trillion dollars and total liabilities of 1.469 trillion dollars.
In other words, there wasn’t much equity there at the end of December, and things have deteriorated rapidly since that time.  In fact, it is being reported that a billion dollars a day is being pulled out of the bank at this point.
I know that most Americans don’t really care if Deutsche Bank lives or dies, but as the New York Post has pointed out, the failure of Deutsche Bank could quickly become a major crisis for the entire global financial system…

Friday, August 17, 2018

10 numbers that prove America’s current financial condition


Related image

America’s long-term “balance sheet numbers” just continue to get progressively worse.  Unfortunately, since the stock market has been soaring and the GDP numbers look okay, most Americans assume that the U.S. economy is doing just fine.  But the stock market was soaring and the GDP numbers looked okay just prior to the great financial crisis of 2008 as well, and we saw how that turned out.  The truth is that GDP is not the best measure for the health of the economy.  Judging the U.S. economy by GDP is basically like measuring the financial health of an individual by how much money he or she spends, and I will attempt to illustrate that in this article.

#1 U.S. consumer credit just hit another all-time record high.  In the second quarter of 2008, total consumer credit reached a grand total of 2.63 trillion dollars, and now ten years later that number has soared to 3.87 trillion dollars.  That is an increase of 48 percent in just one decade.

#2 Student loan debt has surpassed 1.5 trillion dollars for the first time ever.  Over the last 8 years, the total amount of student loan debt has shot up 79 percent in the United States.

#3 According to the Federal Reserve, the credit card default rate in the U.S. has risen for 7 quarters in a row.

#4 One recent survey found that 42 percent of American consumers paid their credit card bill late “at least once in the last year”, and 24 percent of Americans consumers paid their credit card bills late “more than once in the last year”.

#5 Real wage growth in the United States just declined by the most that we have seen in 6 years.

#6 According to one recent study, the “rate of people 65 and older filing for bankruptcy is three times what it was in 1991”.

#7 We are in the midst of the greatest “retail apocalypse” in American history.  At this point, 57 major retailers have announced store closings so far in 2018.

#8 The size of the official U.S. budget deficit is up 21 percent under President Trump.

#9 It is being projected that interest on the national debt will surpass half a trillion dollars for the first time ever this year.

#10 Goldman Sachs is projecting that the yearly U.S. budget deficit will surpass 2 trillion dollars by 2028.

US Spending On Interest Hits All Time High

Zero Hedge   08/10/2018
The US' spending problem is starting to become a major issue.
According to the latest Monthly Treasury Statement, in June, the US collected $225BN in tax receipts - consisting of $110BN in individual income tax, $91BN in social security and payroll tax, $4BN in corporate tax and $20BN in other taxes and duties- a drop of 2.9% from the $232BN collected last July and a reversal from the recent increasing trend...

 ... and in July, the 12 month trailing receipt total was barely higher compared to a year ago, up just 0.4% Y/Y after rising as much as 3.1% at the end of 2017.

Meanwhile Federal spending rose, up 9.9% from $275BN last July to $302BN last month.

 ... where the money was spent on social security ($83BN), defense ($49BN), Medicare ($24BN), Interest on Debt ($35BN), and Other ($111BN).

This resulted in a July budget deficit of $77 billion, in line with expectations, and a signification deterioration from the $43 billion recorded in July of 2017.
The July deficit brought the cumulative 2018F budget deficit to over $684BN during the first 10 month of the fiscal year, up 28% over the past year.

Sunday, April 29, 2018

US stock markets are currently passing through the same peaks they faced 11 years ago

RT 13 Apr, 2018
US stock markets are currently passing through the same peaks they faced 11 years ago, right before the massive sell-off that triggered the 2008 financial crisis, according to Phil Town, who sold his stocks before the crash.
“I think we are right on the brink. The logic is pretty straightforward from a fundamental point of view, we are at a relationship between the Wilshire GDP ratio which is almost unprecedented historically, where we have a relationship that is historically the Wilshire's 70 to a 100 percent value of GDP,” the investor told The Street.

Friday, March 16, 2018

Global debt has reached record heights without any signs of relief

Gold Telegraph   03/10/2018
Global debt has reached record heights without any signs of relief. While central bankers try to explain away the phenomenon of these out-of-control numbers, it’s not much of a mystery. Immediate consumption with the promise of repayment sometime in the future has consequences. Global debt is staggering to the point most of it will never be repaid. Certainly not in our generation. Perhaps by our grandchildren, but as global debt keeps mounting, the picture is doubtful.

The per capita global debt is $30,000. Who, exactly, will be making repayments?

Economists insist that the 2007 financial crisis could not have been predicted. Yet, all the signs of out-of-control credit where there. Today, economists are repeating the same mantra, despite the spiraling world debt. The question is not if the next bubble will strike. It’s a matter of when.

The math is fairly simple. The more a country increases its debt to simply stay afloat, the more like the increasing debt will cause a tightening of credit. The next step in the equation is a burst bubble and economic crisis. This is what happened in 1929, happened again in 2007, and it’s happening now. Past behavior is the best predictor of future behavior.

Out-of-control credit will undoubtedly slow down the US’s current economic growth. It probably won’t cause an outright crisis. Other countries may not be as fortunate.

Countries such as China, Belgium, South Korea, Australia, and Canada are experiencing an unprecedented credit bubble, with few systems in place to control it. The resulted inflation or simply write-offs of debts could result in a global financial disaster we have not seen before. The current economic upswing is unlikely to continue.

Prior to 2007, globalization, the exchange of goods and services between countries, was at its highest level. Since then, globalization has leveled off. We may have seen the peak of globalization. Emerging countries, benefiting from globalization, have raised their standard of living and cheap goods are no longer crossing borders with the same abandon. Countries are instituting nationalistic protectionist measures to protect their own economy. Globalization is giving way to “islandization,” where the movement of capital and good across borders is being limited instead of expanded. This limited global trading, along with rising geopolitical tensions, will negatively affect global economic expansion, while the global debt is still spiraling out of control.

Saturday, January 20, 2018

Stock market optimism from pros reaches highest level in nearly 32 years


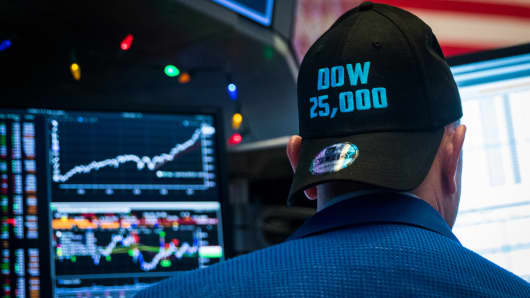
A trader wears a DOW 24,000 hat as he works on the floor of the New York Stock Exchange, (NYSE) as the Dow Jones Industrial Average crosses 25,000 on Jan. 4ht, 2018 for the first time.

CNBC  Wed, 17 Jan 2018
Stock market optimism among professional investors just keeps on surging, and is now at the highest levels since before the crash of 1987.
Bullishness, or the belief that the market is heading higher, is now at 66.7 percent in the latest Investors Intelligence survey, a widely followed gauge of sentiment among investment newsletter authors.
That's the highest level since early April 1986 — a potential warning sign that the rush into equities is getting overdone. After all, a year after the bulls had reached this level came the infamous Black Monday crash that sent the Dow Jones industrials down nearly 22 percent in a single day.

Wednesday, October 4, 2017

Goldman Sachs considers trading bitcoin & other cryptocurrencies


Goldman Sachs considers trading bitcoin & other cryptocurrencies

RT, 3 Oct, 2017
A new trading operation dedicated to digital currencies is being explored by Goldman Sachs, sources told the Wall Street Journal. It could be the first blue-chip Wall Street firm to deal directly in the growing yet controversial cryptocurrency market. 
“In response to client interest in digital currencies, we are exploring how best to serve them in this space,” said an unnamed Goldman spokeswoman.
According to people familiar with the matter, Goldman’s effort involves both its currency trading division and the bank’s strategic investment group. The firm sees bitcoin’s future more as a payment method rather than a store of value.

Sources also said Goldman’s effort is in its early stages and may not proceed. The firm’s interest, however, could strengthen bitcoin’s position as digital currencies were initially viewed as havens for illicit activity.
Big banks such as UBS, Barclays, ING, Goldman Sachs and BNY Mellon have recently announced ventures into the blockchain technology that allows digital currencies to function and be transferred safely.
BNP Paribas has said it is looking to add bitcoin to one of its currency funds and has been doing "beta testing" involving the cryptocurrency.
Societe Generale and JPMorgan even published job offers for an IT developer and technician on bitcoin, blockchains, and cryptocurrencies.

Morgan Stanley Chief Executive James Gorman said bitcoin is “obviously highly speculative, but it’s not inherently bad.”
According to research firm Autonomous NEXT, around 70 hedge funds are currently investing in cryptocurrencies.
Control over virtual currencies’ trading platforms has been tightened recently to prevent them from becoming money laundering sites.
Last month, Chinese authorities cracked down on cryptocurrencies, ordering the country’s exchanges to suspend operations. Beijing banned initial coin offerings (ICOs), referring to them as an unauthorized fundraising tool that may involve financial scams.
The move was followed by South Korea, with the country’s financial regulator saying it will ban money raising through all forms of virtual currencies.
In July, the US Securities and Exchange Commission warned that some ICOs should be regulated like other securities. Authorities in Singapore and Canada have issued similar warnings.        RT

Tuesday, February 23, 2016

The US Economy Has Not Recovered and Will Not Recover


  February 17, 2016

The US economy died when middle class jobs were offshored and when the financial system was deregulated.
Jobs offshoring benefitted Wall Street, corporate executives, and shareholders, because lower labor and compliance costs resulted in higher profits. These profits flowed through to shareholders in the form of capital gains and to executives in the form of “performance bonuses.” Wall Street benefitted from the bull market generated by higher profits.
However, jobs offshoring also offshored US GDP and consumer purchasing power. Despite promises of a “New Economy” and better jobs, the replacement jobs have been increasingly part-time, lowly-paid jobs in domestic services, such as retail clerks, waitresses and bartenders.
The offshoring of US manufacturing and professional service jobs to Asia stopped the growth of consumer demand in the US, decimated the middle class, and left insufficient employment for college graduates to be able to service their student loans. The ladders of upward mobility that had made the United States an “opportunity society” were taken down in the interest of higher short-term profits.
Without growth in consumer incomes to drive the economy, the Federal Reserve under Alan Greenspan substituted the growth in consumer debt to take the place of the missing growth in consumer income. Under the Greenspan regime, Americans’ stagnant and declining incomes were augmented with the ability to spend on credit. One source of this credit was the rise in housing prices that the Federal Reserves low inerest rate policy made possible. Consumers could refinance their now higher-valued home at lower interest rates and take out the “equity” and spend it.
The debt expansion, tied heavily to housing mortgages, came to a halt when the fraud perpetrated by a deregulated financial system crashed the real estate and stock markets. The bailout of the guilty imposed further costs on the very people that the guilty had victimized.
Under Fed chairman Bernanke the economy was kept going with Quantitative Easing, a massive increase in the money supply in order to bail out the “banks too big to fail.” Liquidity supplied by the Federal Reserve found its way into stock and bond prices and made those invested in these financial instruments richer. Corporate executives helped to boost the stock market by using the companies’ profits and by taking out loans in order to buy back the companies’ stocks, thus further expanding debt.
Those few benefitting from inflated financial asset prices produced by Quantitative Easing and buy-backs are a much smaller percentage of the population than was affected by the Greenspan consumer credit expansion. A relatively few rich people are an insufficient number to drive the economy.
The Federal Reserve’s zero interest rate policy was designed to support the balance sheets of the mega-banks and denied Americans interest income on their savings. This policy decreased the incomes of retirees and forced the elderly to reduce their consumption and/or draw down their savings more rapidly, leaving no safety net for heirs.
Using the smoke and mirrors of under-reported inflation and unemployment, the US government kept alive the appearance of economic recovery. Foreigners fooled by the deception continue to support the US dollar by holding US financial instruments.
The official inflation measures were “reformed” during the Clinton era in order to dramatically understate inflation. The measures do this in two ways. One way is to discard from the weighted basket of goods that comprises the inflation index those goods whose price rises. In their place, inferior lower-priced goods are substituted.
For example, if the price of New York strip steak rises, round steak is substituted in its place. The former official inflation index measured the cost of a constant standard of living. The “reformed” index measures the cost of a falling standard of living.
The other way the “reformed” measure of inflation understates the cost of living is to discard price rises as “quality improvements.” It is true that quality improvements can result in higher prices. However, it is still a price rise for the consumer as the former product is no longer available. Moreover, not all price rises are quality improvements; yet many prices rises that are not can be misinterpreted as “quality improvements.”
These two “reforms” resulted in no reported inflation and a halt to cost-of-living adjustments for Social Security recipients. The fall in Social Security real incomes also negatively impacted aggregate consumer demand.
The rigged understatement of inflation deceived people into believing that the US economy was in recovery. The lower the measure of inflation, the higher is real GDP when nominal GDP is deflated by the inflation measure. By understating inflation, the US government has overstated GDP growth.
What I have written is easily ascertained and proven; yet the financial press does not question the propaganda that sustains the psychology that the US economy is sound. This carefully cultivated psychology keeps the rest of the world invested in dollars, thus sustaining the House of Cards.
John Maynard Keynes understood that the Great Depression was the product of an insufficiency of consumer demand to take off the shelves the goods produced by industry. The post-WW II macroeconomic policy focused on maintaining the adequacy of aggregate demand in order to avoid high unemployment. The supply-side policy of President Reagan successfully corrected a defect in Keynesian macroeconomic policy and kept the US economy functioning without the “stagflation” from worsening “Philips Curve” trade-offs between inflation and employent. In the 21st century, jobs offshoring has depleted consumer demand’s ability to maintain US full employment.
The unemployment measure that the presstitute press reports is meaningless as it counts no discouraged workers, and discouraged workers are a huge part of American unemployment. The reported unemployment rate is about 5%, which is the U-3 measure that does not count as unemployed workers who are too discouraged to continue searching for jobs.
The US government has a second official unemployment measure, U-6, that counts workers discouraged for less than one-year. This official rate of unemployment is 10%.
When long term (more than one year) discouraged workers are included in the measure of unemployment, as once was done, the US unemployment rate is 23%. (See John Williams, shadowstats.com)
Fiscal and monetary stimulus can pull the unemployed back to work if jobs for them still exist domestically. But if the jobs have been sent offshore, monetary and fiscal policy cannot work.
What jobs offshoring does is to give away US GDP to the countries to which US corporations move the jobs. In other words, with the jobs go American careers, consumer purchasing power and the tax base of state, local, and federal governments. There are only a few American winners, and they are the shareholders of the companies that offshored the jobs and the executives of the companies who receive multi-million dollar “performance bonuses” for raising profits by lowering labor costs. And, of course, the economists, who get grants, speaking engagements, and corporate board memberships for shilling for the offshoring policy that worsens the distribution of income and wealth. An economy run for a few only benefits the few, and the few, no matter how large their incomes, cannot consume enough to keep the economy growing.
In the 21st century US economic policy has destroyed the ability of real aggregate demand in the US to increase. Economists will deny this, because they are shills for globalism and jobs offshoring. They misrepresent jobs offshoring as free trade and, as in their ideology free trade benefits everyone, claim that America is benefitting from jobs offshoring. Yet, they cannot show any evidence whatsoever of these alleged benefits. (See my book, The Failure of Laissez Faire Capitalism and Economic Dissolution of the West.) http://www.amazon.com/Failure-Laissez-Faire-Capitalism/dp/0986036250/ref=sr_1_1?s=books&ie=UTF8&qid=1455746560&sr=1-1&keywords=paul+craig+roberts-the+failure+of+laissez-faire+capitalism
As an economist, it is a mystery to me how any economist can think that a population that does not produce the larger part of the goods that it consumes can afford to purchase the goods that it consumes. Where does the income come from to pay for imports when imports are swollen by the products of offshored production?
We were told that the income would come from better-paid replacement jobs provided by the “New Economy,” but neither the payroll jobs reports nor the US Labor Departments’s projections of future jobs show any sign of this mythical “New Economy.”
There is no “New Economy.” The “New Economy” is like the neoconservatives promise that the Iraq war would be a six-week “cake walk” paid for by Iraqi oil revenues, not a $3 trillion dollar expense to American taxpayers (according to Joseph Stiglitz and Linda Bilmes) and a war that has lasted the entirely of the 21st century to date, and is getting more dangerous.
The American “New Economy” is the American Third World economy in which the only jobs created are low productivity, low paid nontradable domestic service jobs incapable of producing export earnings with which to pay for the goods and services produced offshore for US consumption.
The massive debt arising from Washington’s endless wars for neoconservative hegemony now threaten Social Security and the entirety of the social safety net. The presstitute media are blaming not the policy that has devasted Americans, but, instead, the Americans who have been devasted by the policy.
Earlier this month I posted readers’ reports on the dismal job situation in Ohio, Southern Illinois, and Texas. In the March issue of Chronicles, Wayne Allensworth describes America’s declining rural towns and once great industrial cities as consequences of “globalizing capitalism.” A thin layer of very rich people rule over those “who have been left behind”—a shrinking middle class and a growing underclass. According to a poll last autumn, 53 percent of Americans say that they feel like a stranger in their own country.
Most certainly these Americans have no political representation. As Republicans and Democrats work to raise the retirement age in order to reduce Social Security outlays, Princeton University experts report that the mortality rates for the white working class are rising. The US government will not be happy until no one lives long enough to collect Social Security.
The United States government has abandoned everyone except the rich.
In the opening sentence of this article, I said that the two murderers of the American economy were jobs offshoring and financial deregulation. Deregulation greatly enhanced the ability of the large banks to financialize the economy. Financialization is the diversion of income streams into debt service. When debt service absorbs a large amount of the available income, the economy experiences debt deflation. The service of debt leaves too little income for purchases of goods and services and prices fall.
Michael Hudson, who I recently wrote about, is the expert on finanialization. His book, Killing the Host, which I recommended to you, tells the complete story. Briefly, financialization is the process by which creditors capitalize an economy’s economic surplus into interest payments to themselves. Perhaps an example would be a corporation that goes into debt in order to buy back its shares. The corporation achieves a temporary boost in its share prices at the cost of years of interest payments that drain the corporation of profits and deflate its share price.
Michael Hudson stresses the conversion of the rental value of real estate into mortgage payments. He emphasizes that classical economists wanted to base taxation not on production, but on economic rent. Economic rent is value due to location or to a monopoly position. For example, beachfront property has a higher price because of location. The difference in value between beachfront and nonbeachfront property is economic rent, not a produced value. An unregulated monopoly can charge a price for a service that is higher than the price that would bring that service unto the market.
The proposal to tax economic rent does not mean taxing you on the rent that you pay your landlord or taxing your landlord on the rent that you pay him such that he ceases to provide the housing. By economic rent Hudson means, for example, the rise in land values due to public infrastructure projects such as roads and subway systems. The rise in the value of land opened by a new road and housing and in commercial space along a new subway line is not due to any action of the property owners. This rise in value could be taxed in order to pay for the project instead of taxing the income of the population in general. Instead, the rise in land values raises appraisals and the amount that creditors are willing to lend on the property. New purchasers and existing owners can borrow more on the property, and the larger mortgages divert the increased land valuation into interest payments to creditors. Lenders end up as the major beneficiaries of public projects that raise real estate prices.
Similarly, unless the economy is financialized to such an extent that mortgage debt can no longer be serviced, when central banks lower interest rates property values rise, and this rise can be capitalized into a larger mortgage.
Another example would be property tax reductions and legislation such as California’s Proposition 13 that freeze in whole or part the property tax base. The rise in real estate values that escape taxation are capitalized into larger mortgages. New buyers do not benefit. The beneficiaries are the lenders who capture the rise in real estate prices in interest payments.
Taxing economic rent would prevent the financial system from capitalizing the rent into debt instruments that pay interest to the financial sector. Considering the amount of rents available to be taxed, taxing rents would free production from income and sales taxation, thus lowering consumer prices and freeing labor and productive capital from taxation.
With so much of land rent already capitalized into debt instruments shifting the tax burden to economic rent would be challenging. Nevertheless, Hudson’s analysis shows that financialization, not wage suppression, is the main instrument of exploitation and takes place via the financial system’s conversion of income streams into interest payments on debt.
I remember when mortgage service was restricted to one-quarter of household income. Today mortgage service can eat up half of household income. This extraordinary growth crowds out the production of goods and services as less of household income is available for other purchases.
Michael Hudson and I bring a total indictment of the neoliberal economics profession, “junk economists” as Hudson calls them.             UNZ